Have you ever found that inventory records are not in line with the amount of physical goods in the warehouse? This kind of incompatibility can become a serious problem, especially if left without a solution.
Stock opname comes as an important step to overcome the inaccuracy of inventory data.
Non-conformity not only disrupts smooth operations, but also opens up opportunities for fraud or irregularities in goods.
Without waiting any longer, let's take a deeper look at what an overnight stock is and how to do it so that previous risks can be avoided!
What is a Stock Opname?
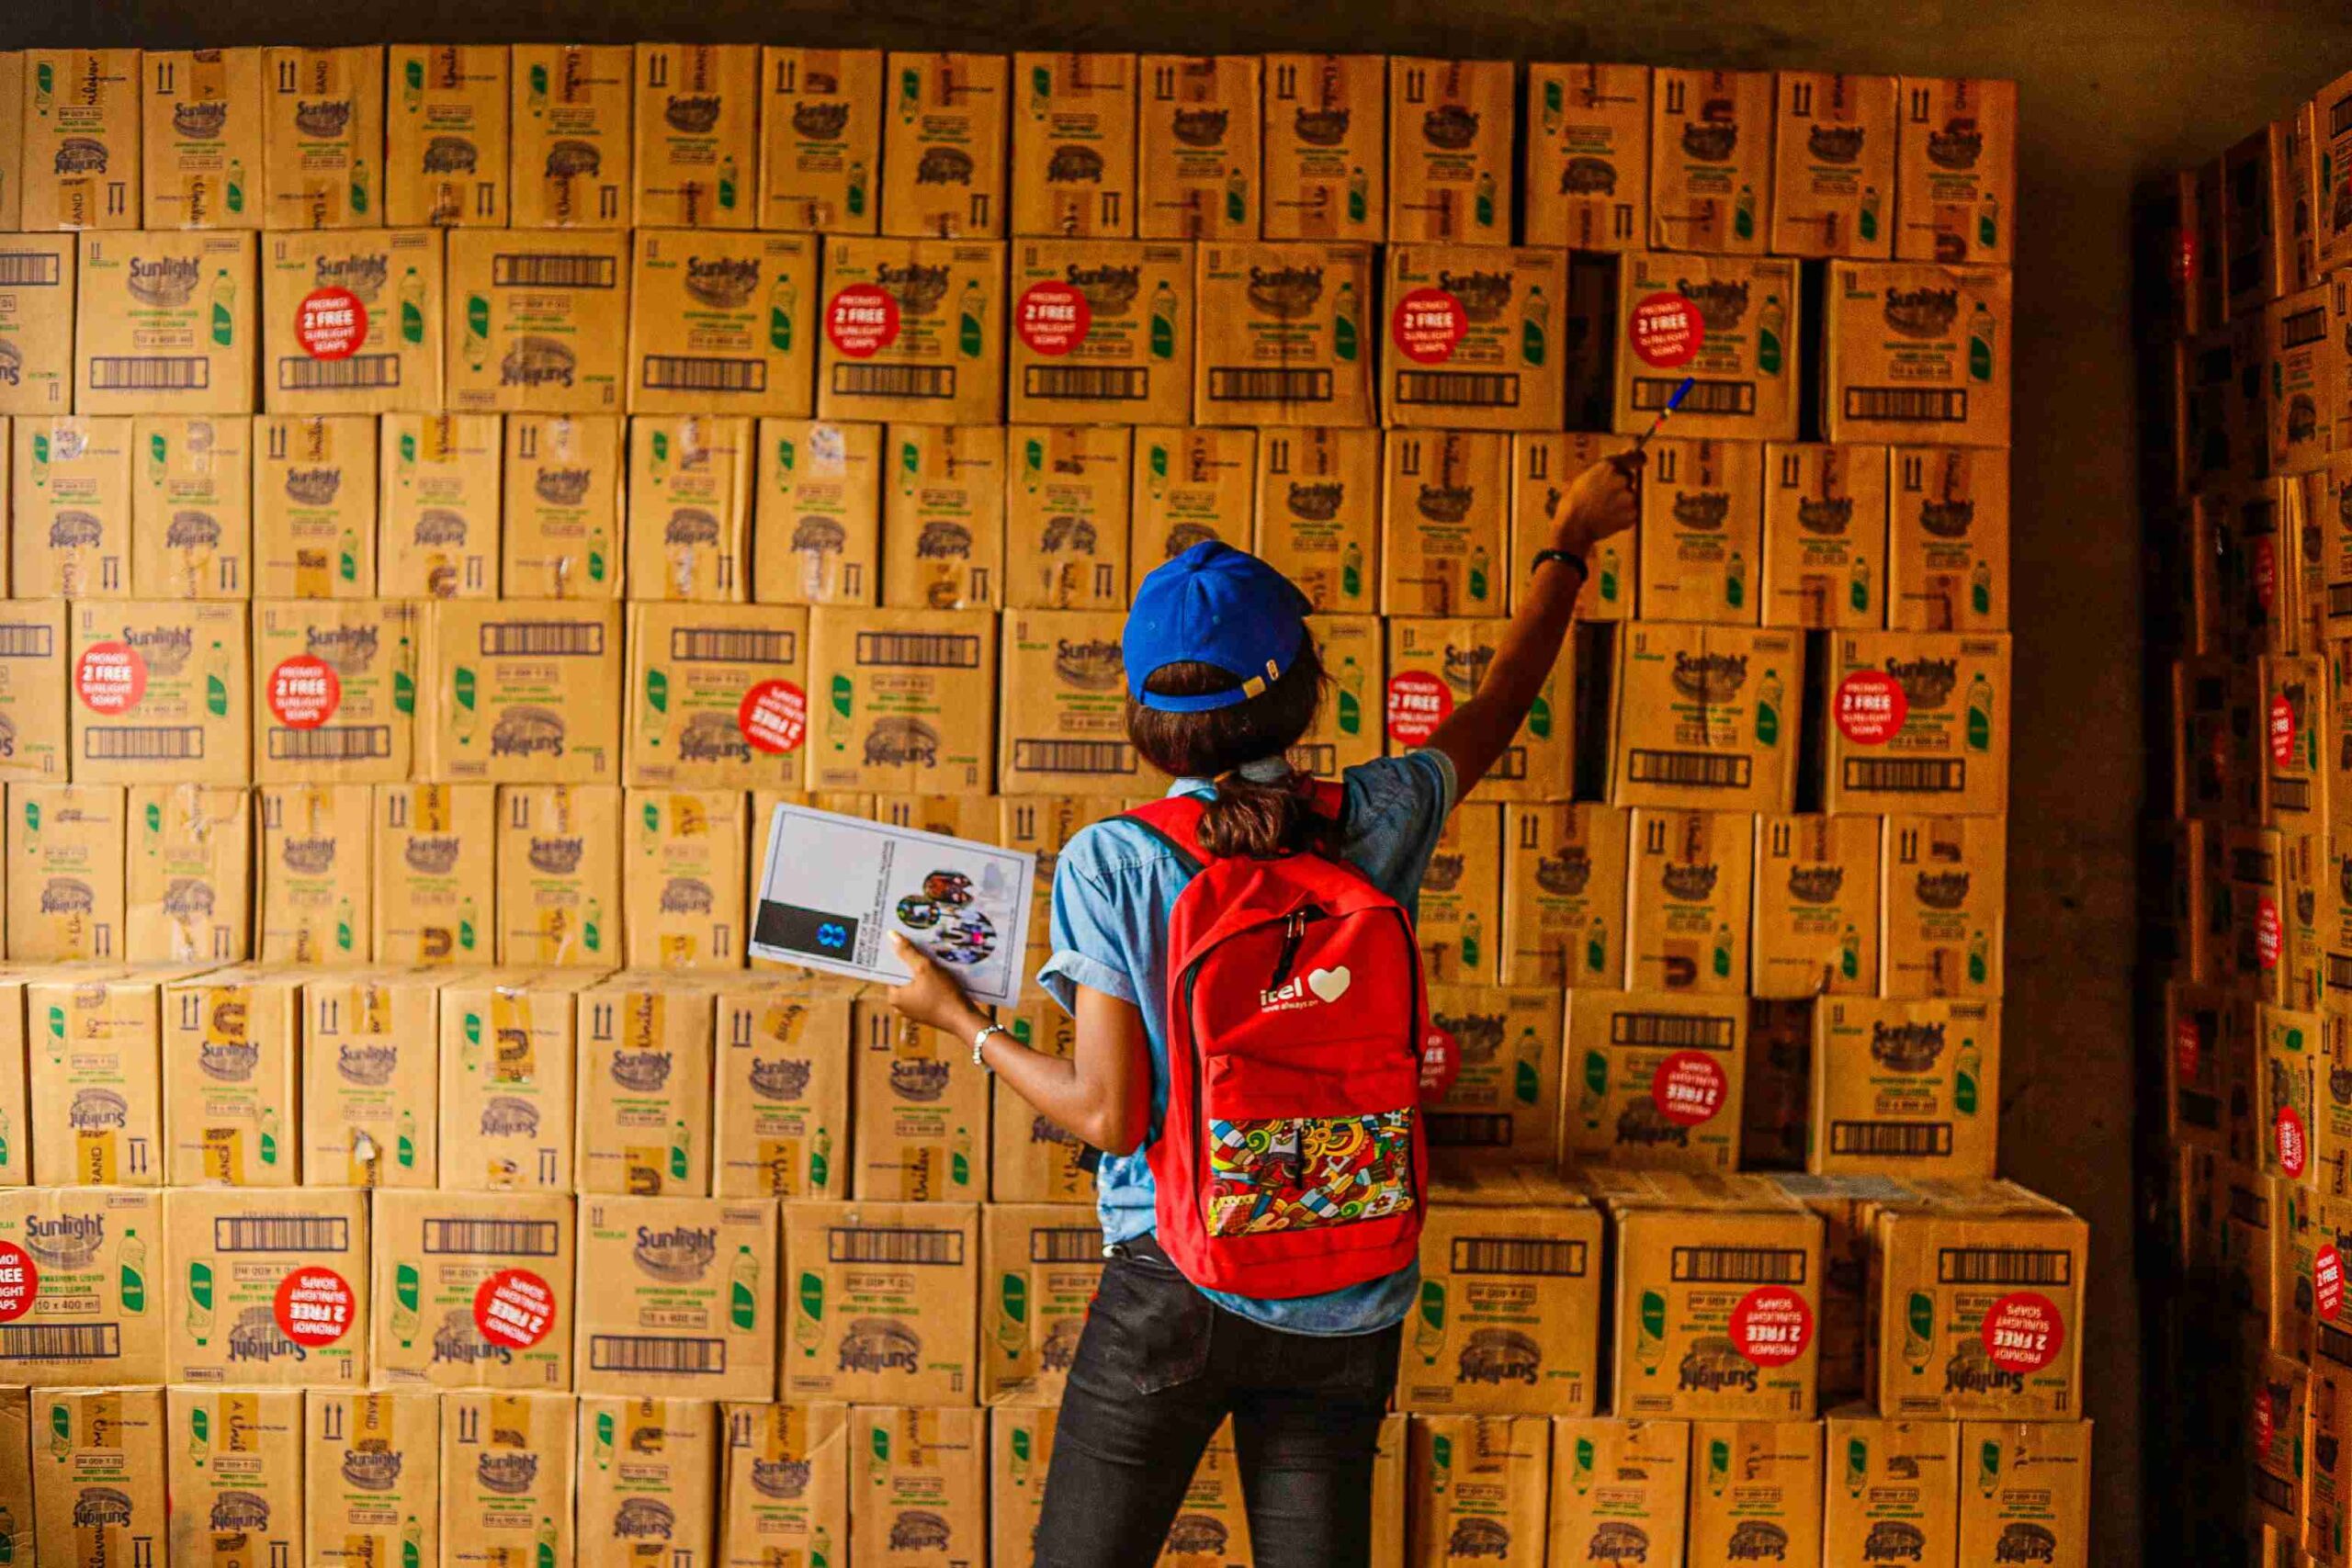
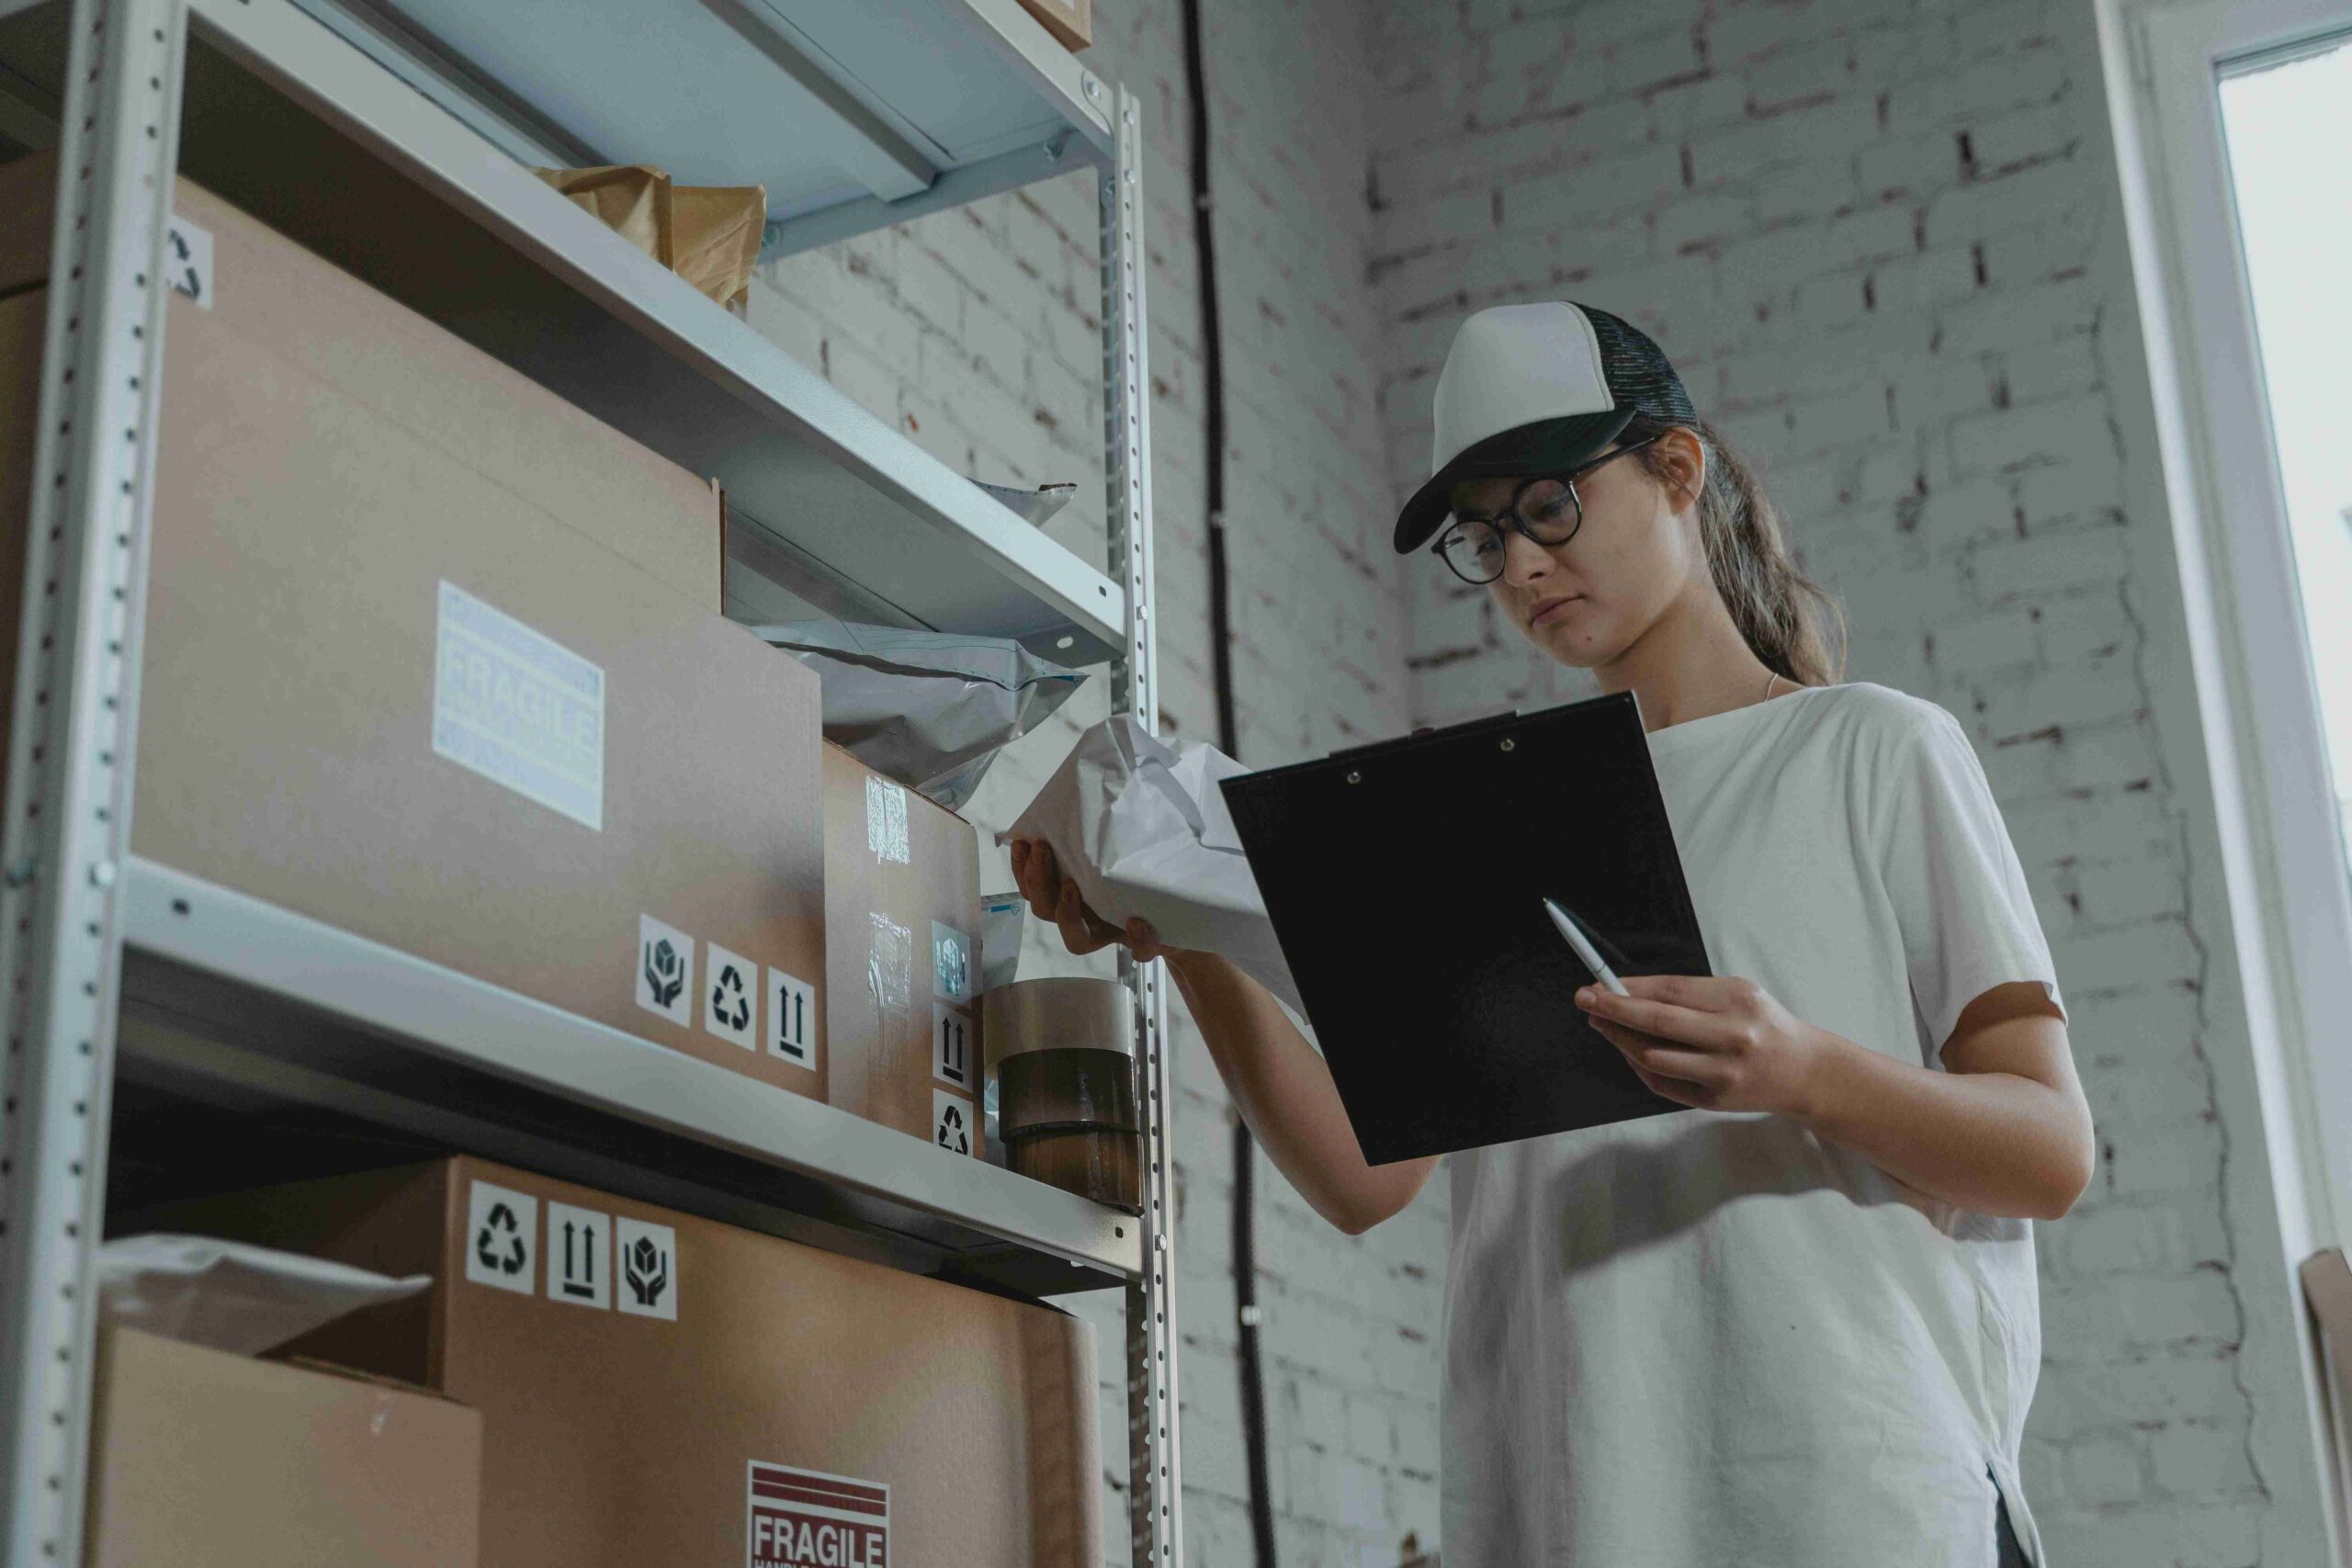
Stock opname is the activity of physically counting inventory, then matching the results with accounting records or stock data in the system. Differences found are traced and, where necessary, used as a basis for adjusting the records. In accounting terms, this activity is equivalent to a physical inventory count (physical inventory count). Two frequently cited accounting references define it as follows:
- Sunarto (2002): Stock opname is a physical check of inventory to ensure the accounting records are correct, and is part of the internal control system.
- Toto Sucipto (2006): Stock opname is a periodic count of finished goods, that is, physically counting the goods in the warehouse and then matching them with accounting records or stock data.
In practice, this activity includes preparing the area and documents, physical counting, comparison with records, tracing differences, and adjusting records where necessary.
The count is often accompanied by checks on the condition of goods, for example damaged, expired, or obsolete goods, before the goods are shipped or used for production.
What Is the Meaning of the Word Opname in Stock Opname?
The word opname comes from the Dutch word opname, formed from the verb opnemen. In Dutch, this word means, among other things, recording or noting, and also the admission of patients to a health facility (Wiktionary).
In Indonesia, the online KBBI records opname with the meaning of inpatient care staying overnight at a hospital. For this reason, many people first know this word from the expression of opname in a hospital, and ask what stock opname means or what opname means in the context of goods.
In the term stock opname, the word opname is taken to mean recording or data collection, so stock opname means physically collecting data on stock. Its English equivalent is often called stocktaking or physical inventory count.
What Is the Purpose of Stock Opname?
In general, stock opname aims to minimize the potential for recording errors so that inventory can be managed properly.
This ensures that the amount of stock is not less or more than what is recorded, so that the company's operational activities can run smoothly.
For example, if the stock in the field turns out to be less than recorded, the company may not be able to meet customer demand on time.
In addition, other objectives are:
1. Prevent Companies From Experiencing Losses
Through stock opname, the company can verify the conformity between the amount of goods owned and the bookkeeping records. Errors in calculations can potentially lead to losses.
For example, there are missing items that are not detected due to lack of supervision when the goods are received, resulting in financial losses for the company.
2. Checking the condition of the goods before shipping
Stock opname also aims to check the physical quality of the goods to prevent the delivery of damaged, expired or defective products.
When damaged goods are shipped, customers will lose trust, causing the business to lose its good reputation.
3. Managing the Inbound and Outbound Goods Process
To monitor the flow of goods more efficiently and prevent discrepancies, companies can conduct inventory counts.
Companies can prevent the loss of goods or discrepancies between shipped and received goods in a more systematic manner.
4. Helping The Success Of The Internal Control System
To create a internal control system successful, the stock calculation should not be missed.
When the stock calculation results do not match the listing, the company can identify and resolve them more quickly.
Thus, the room for internal parties to manipulate stock data in ways that harm the company becomes narrower.
5. Simplify The Process Of Goods Restock
Inventory levels can be maintained through a routine inventory calculation process.
When stocks begin to run low, companies can improve production processes.
Conversely, companies can also avoid excess inventory by implementing more efficient production planning.
6. Identify popular products in the market
The results of an inventory count can also give early clues about demand patterns. Products that often run out can indicate high demand, but this should be checked against sales data because stockouts can also be caused by supply delays or recording errors.
With this information, the company can adjust the production system to meet customer needs more optimally.
Who Is Involved?
Responsibility for stock opname lies with company management, which sets the procedures and appoints the counting team. In a financial statement audit, the counting instructions and procedures are also treated as management's responsibility, while the auditor evaluates and observes them.
The principle of segregation of duties must be maintained. The party that stores goods or records inventory should not be the only counter, to avoid bias and potential fraud. Warehouse staff are still involved to open access and recognize the goods, while the count results are verified by a party independent of the warehouse, for example the accounting team or internal audit.
If discrepancies are found during the review, management can evaluate corrective actions and determine who is responsible for ensuring that the error does not recur.
When Is the Ideal Time to Conduct a Stock Count?
The timing of the inventory count is tailored to each company’s specific needs.
The inventory counting period can be selected from several options, including daily, weekly, monthly, quarterly, semiannual, seasonal, and even annual.
Determination of the implementation time of stock opname is based on several factors, including the type and characteristics of the business, the volume and turnover of stock, as well as the availability of resources.
For example, large retailers with high transaction levels often use incremental counting (cycle count) of certain groups of goods periodically, rather than counting the whole warehouse every day. As a general benchmark, audit standards state that management ordinarily counts inventory physically at least once a year (ISA 501 paragraph A1).
Meanwhile, fashion companies can schedule stock opname before and after certain seasons to evaluate stock.
What Are the Types of Stock Opname?
Accounting standards do not standardize a classification of stock opname types. The division below is commonly used in practice, and the terms may differ between companies.
| Types | How it works | Suitable for |
|---|---|---|
| Comprehensive | All types of goods are counted at one time, usually at period end or year end. Movement of goods in and out is generally paused temporarily. | Warehouses with a limited number of items or preparation of annual financial statements. |
| Periodic | Scheduled regularly, for example monthly, quarterly, or semiannually. | Companies that have a scheduled counting policy. |
| Cyclical (cycle count) | Goods are counted in stages by group or category on a rotating schedule, for example one category every week. | Large warehouses that find it hard to stop operating. |
| Partial | Only certain goods are counted, namely high-risk goods or goods crucial to operations. | High-value goods or goods prone to discrepancies. |
| Incidental | Triggered by a specific event outside the schedule, for example a disaster, a major sales campaign, or suspected loss of goods. | Special conditions that require an immediate check. |
What Is the Role of Stock Opname in Periodic and Perpetual Systems?
The role of stock opname depends on the inventory recording system the company uses.
| The system | How it is recorded | Role of stock opname |
|---|---|---|
| Periodic | Inventory and cost of goods sold (COGS) are only calculated at period end. | The physical count determines the value of ending inventory. COGS = beginning inventory + net purchases minus ending inventory. |
| Perpetual | Inventory and COGS are updated with every transaction. | The physical count tests whether the records are still reliable. A discrepancy indicates a problem in controls. |
Audit standards recognize this. In a perpetual system, management may carry out a physical count to confirm the reliability of the records, and differences between the records and the physical quantity may indicate that controls over changes in inventory are not operating effectively (ISA 501 paragraphs A1 and A10).
For an example of application in the plantation sector, also read strategies for digitalizing stock opname and plantation asset audits.
Sample Stock Opname
The result of the stock calculation process is a report showing the physical condition of the goods in the warehouse. Here we present some reports as illustrative examples of stock opname in the company.
1. Examples Of Physical Goods Stock Opname
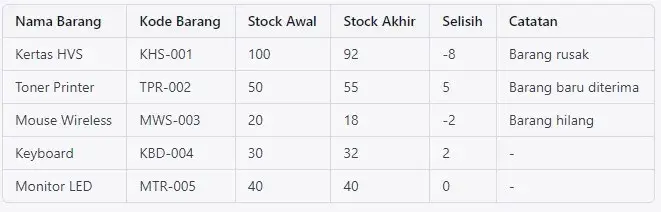
The report comes from the process of capturing physical goods data directly.
Through the sample report, a company can compare the stock from the physical count with the stock per accounting records, then find the difference.
2. Examples Of Stock Opname By Period
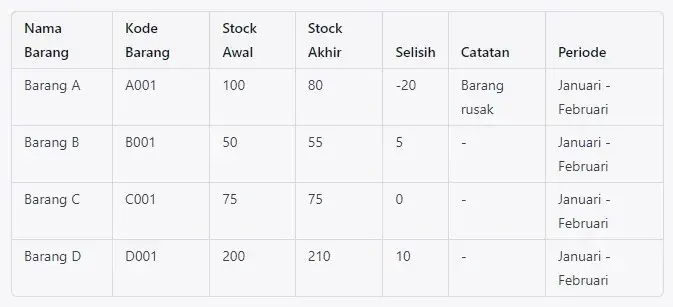
In this example, the calculation is carried out within a certain time range. Businesses can find out if there are errors in bookkeeping in certain periods.
3. An Example Of The Total Stock
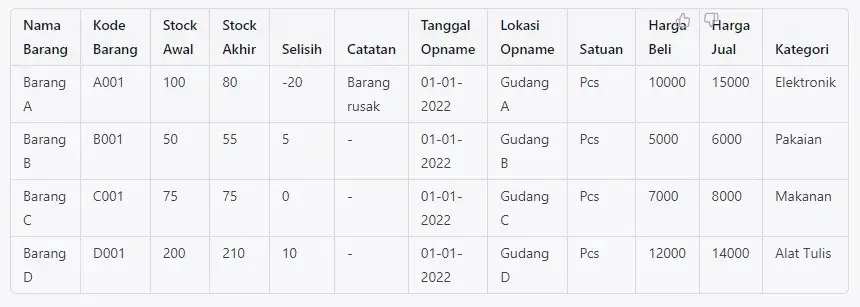
In this stock calculation report, recording covers all aspects, ranging from the location of the opname, selling price and purchase price, to the category of goods, everything will be recorded in detail.
Calculations are also made on all goods produced by the enterprise.
4. Partial Stock Opname Example
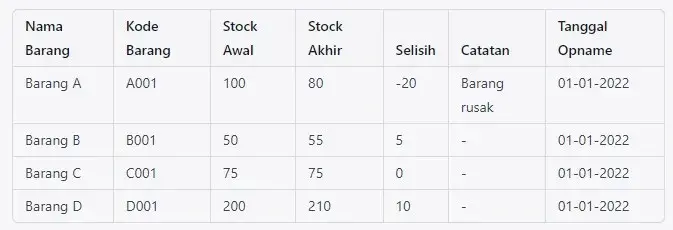
The last example is a partial stock calculation. In this method, not all items are counted, only certain items.
These items are those that have the highest risk of bookkeeping errors or are crucial to business operations.
5. Example of Calculating a Stock Opname Difference
A stock opname difference is calculated by comparing the stock from the physical count with the stock per records:
Difference (units) = physical stock minus system stock
Difference value = difference (units) multiplied by cost per unit
A positive result means physical stock is greater than the records (surplus), while a negative result means physical stock is lower (shortage). The figures below are for illustration only:
| Item | System stock | Physical stock | Difference (units) | Cost per unit | Difference value |
|---|---|---|---|---|---|
| Packaging box A | 120 | 118 | -2 | Rp25.000 | -Rp50.000 |
| Bottle B | 80 | 83 | +3 | Rp10.000 | +Rp30.000 |
| Shelf C | 45 | 45 | 0 | Rp40.000 | Rp0 |
| Total | -Rp20.000 |
Do not immediately assume a difference is a loss. First trace the possible causes, such as incoming or outgoing transactions not yet recorded, input errors or wrong units, miscounts, damaged or expired goods not yet written off, and even loss or theft. Recount items with large differences before the records are adjusted.
6. Example of an Adjusting Journal Entry for Differences
After the difference is traced and approved by management, the accounting team adjusts the records. Handling of differences follows company policy. Some charge it to an expense account, while others ask the responsible staff for reimbursement. Below is an illustrative journal entry from the example above (account names adjusted to the company's chart of accounts):
| Condition | Account | Debit | Credit |
|---|---|---|---|
| Shortage of Rp50,000 (Packaging box A) | Inventory difference expense | Rp50.000 | |
| Inventory | Rp50.000 | ||
| Surplus of Rp30,000 (Bottle B) | Inventory | Rp30.000 | |
| Inventory difference (offsetting account per company policy) | Rp30.000 |
How to Conduct a Good Stock Opname?
The stock calculation process is not complicated. You can do this through the following steps:
1. Arranging Goods and Initial Preparation
One week before implementation, you can arrange items by category or code to make calculations easier.
Label, tag, or barcode effective to distinguish items that have been calculated with those that have not.
Items that do not need to be counted must also be given a special mark, for example “not counted”. Examples are consigned goods or goods held for another party, goods received after the counting cut-off time (cut-off), and damaged goods to be written off.
2. Coordinating the Team and Freezing Goods Movements
The day before the stock opname, a briefing needs to be held to the team involved to provide an understanding of roles and responsibilities.
In addition, make sure all item mutations have been inputted until the closing hours of operations on that day. Finally, additional item mutations should not occur until the stock opname process is complete.
3. Stages of implementation of stock recording and counting
On the day of the count, the steps to take are:
- Ensure all the latest transactions have been recorded in the system then printed and submitted to the accounting team or audit as a reference calculation.
- Perform physical counting of goods according to categories by marking each item that has been counted with labels or tags.
- Record the physical count results and compare them with the data in the system.
- If there is a difference, recount to ensure there is no error, then trace the cause before the records are adjusted.
4. Make A Report
The report serves as proof that the inventory count has been successfully completed.
Further, the report must be provided to the accounting or audit as material for testing. The same report, often set out in a stock opname record, is given to management for evaluation and to the accounting team to adjust the inventory quantity in the books after the differences are traced and approved.
What Is the Accounting Standards Basis for Stock Opname?
As of 14 October 2026, the accounting standard for inventory in Indonesian financial accounting standards is PSAK 202 Inventories, previously numbered PSAK 14. According to IAI, the renumbering of PSAK and ISAK took effect on 1 January 2024 and did not change the content of the standards.
PSAK 202 refers to IAS 2 and governs the measurement of inventory at the lower of cost and net realizable value. This standard does not govern the technicalities of stock opname. However, the physical count confirms that the quantities measured are correct, and findings of damaged or obsolete goods during the opname can be a basis for assessing impairment of inventory.
What Is the Difference Between Stock Opname and an Inventory Audit?
The two are often confused. Stock opname is a management activity to match the records with the physical condition. An inventory audit is carried out by a party that assesses, and the conduct of the stock opname is one of the things observed.
| Aspect | Stocktaking | Inventory audit |
|---|---|---|
| Purpose | Match the records to the physical condition of goods. | Obtain audit evidence that is sufficient and appropriate about the existence and condition of inventory. |
| Executor | A team appointed by management, for example logistics, warehouse, and accounting. | Internal auditor or external auditor. |
| Main activities | Count, record, compare, and trace differences. | Evaluate management procedures, observe the count, inspect goods, and perform test counts. |
| Results | A count record and adjustment of inventory records. | Working papers, findings, and conclusions on controls and inventory balances. |
| Responsibility | Company management. | The auditor assesses management's count and does not take over the counting. |
How Do Auditors Observe a Stock Opname?
Observation of the physical inventory count is governed by SA 501 (Audit Evidence, Specific Considerations for Selected Items), which is sourced from ISA 501 issued by the IAASB. If inventory is material to the financial statements, the auditor must obtain sufficient appropriate audit evidence about the existence and condition of inventory. To do so, the auditor attends the physical count, unless this is impracticable, in order to:
- Evaluate management's instructions and procedures for recording and controlling the count results.
- Observe the performance of management's count procedures.
- Inspect the inventory.
- Perform test counts (test count).
In addition, the auditor performs procedures on the final inventory records to ensure they reflect the actual count results (ISA 501 paragraph 4). This standard is aimed at financial statement auditors. Internal audit teams are not directly bound by it, but can use its sequence of procedures as a reference, especially for audit procedure prepared in the work program.
What does the auditor examine in management's counting procedures?
Examples of matters assessed in the counting instructions and procedures (ISA 501 paragraph A4):
- Control over count sheets, including used and unused sheets, as well as counting and recounting procedures.
- Accuracy in identifying obsolete, damaged, slow-moving goods, and goods owned by third parties, for example consignment.
- Procedures for estimating the physical quantity when goods cannot be counted by unit, for example piles of coal.
- Controls over movement of goods between locations and shipment and receipt of goods before and after the cut-off.
What does a test count by the auditor look like?
The auditor selects a number of items from management's count records and traces them to the physical goods, and conversely selects physical goods and traces them to the count records. These two directions provide evidence about the completeness and accuracy of the count records (ISA 501 paragraph A7). Note that inspecting goods helps confirm the existence of inventory, but does not necessarily show its ownership (paragraph A6).
What if the count is not on the financial statement date or the auditor cannot attend?
- Count on another date: the auditor adds procedures to ensure that changes in inventory between the count date and the financial statement date are recorded correctly (paragraph 5).
- Unable to attend due to unforeseen circumstances: the auditor counts or observes part of the count on another date and tests the transactions in between (paragraph 6).
- Attendance is impracticable: the auditor performs alternative procedures, and if that is not possible, the audit opinion is modified (paragraph 7).
- Inventory is in the custody of a third party: the auditor requests confirmation from the third party or performs inspection (paragraph 8).
Note as of 14 October 2026: the provisions above are sourced from the text of ISA 501 currently in force. According to the IAASB project page, the IAASB is drafting a revision of ISA 501 for the inventory part. Monitor the official IAPI standards for developments.
FAQ About Stock Opname
What is stocktaking?
Stocktaking is the activity of counting the quantity of goods in the warehouse and then matching it with the company's accounting records. The process includes preparation, physical counting, comparison with records, tracing differences, and adjusting records where necessary.
What is the purpose of a stocktaking?
Preventing losses from record discrepancies, checking the condition of goods before shipping so no damaged or expired products go out, managing the flow of goods in and out, supporting the success of the internal control system, easing the restockprocess, and identifying products that are popular in the market.
Who should perform a stocktaking?
Management is responsible for setting procedures and appointing the counting team. The party that stores goods or records inventory should not be the only counter, to avoid bias and potential fraud.
When is the ideal time to perform a stocktaking?
It can be daily, weekly, monthly, quarterly, semiannual, seasonal, up to annual, depending on the type of business, the volume and turnover of stock, and the availability of resources. Audit standards state that a physical count is ordinarily carried out at least once a year. Large retailers often use incremental counting (cycle count), whereas fashion companies can schedule it before and after certain seasons.
How do you perform a stocktaking that is good?
Four steps: arranging goods by category and labeling them about a week beforehand, coordinating the team through a briefing while freezing stock movements, performing the physical count and comparing it with system data, and preparing a report submitted to the accounting or audit team and management.
What are the types of reports from a stocktaking?
Four forms: physical goods reports from direct data collection, per-period reports to find bookkeeping errors within a certain range, comprehensive reports recording location, selling and buying prices, and goods categories, and partial reports counting only high-risk goods or those crucial to operations.
What is the meaning of the word opname?
Opname was borrowed from the Dutch word opname (from opnemen) which means, among other things, recording or noting. KBBI records it as inpatient care staying overnight at a hospital, whereas in stocktaking this word is used to mean physically collecting data on stock.
What is the formula for the difference in stocktaking?
Difference (units) = physical stock minus system stock. Difference value = difference (units) multiplied by cost per unit. A positive result means a surplus, a negative result means a shortage.
How should discrepancies in stocktaking?
Recount the items with differences, trace the causes (transactions not yet recorded, input errors, damaged goods, or loss), report to management, then adjust the records through adjusting journal entries once the difference is approved. Other follow-up, such as reimbursement by staff, follows company policy.
What types of stocktaking?
The commonly used divisions are comprehensive, periodic, cyclical (cycle count), partial, and incidental. This division is not a standard classification in accounting standards.
What is the difference between a stocktaking and an inventory audit?
Stocktaking is a physical count by a team appointed by management to adjust the records. An inventory audit is carried out by an auditor to assess that count and obtain evidence about the existence and condition of inventory.
Must auditors attend a stocktaking?
In a financial statement audit, if inventory is material, the auditor must obtain evidence about the existence and condition of inventory and, in principle, attends to observe the physical count, unless this is impracticable. If impracticable, the auditor performs alternative procedures (ISA 501 paragraphs 4 and 7). In an internal audit, attendance follows the audit program that is prepared.
How Does Audit Software Support Stock Opname Audits?
Did you know, stock opname plays an important role in audits by helping to ensure conformity between physical stock and bookkeeping records.
Audit Software such as Audithink does not count stock and is not an inventory system. The physical count is still carried out by the team in the field. What it supports is the surrounding audit work, so that the observation of stock opname is better planned and followed up.
In an inventory audit, the audit team can assess inventory risk through risk assessment, prepare audit planning, and use the audit work program template for stock opname observation procedures.
Notifications remind of schedules and deadlines, follow-up monitoring tracks the resolution of differences found, and automatic reports summarize the results for management.
Contact we are now!