An audit opinion is a formal statement issued by an auditor regarding the fairness of the presentation of an entity's financial statements, based on applicable auditing standards. This opinion is the final conclusion of the entire audit process and determines the extent to which the financial reports can be relied upon by stakeholders—from management, investors, regulators, to the public.
According to the currently applicable Auditing Standards, there are 4 types of audit opinion: unqualified opinion, qualified opinion, adverse opinion, and disclaimer of opinion. Some references mention five — the explanation for that difference is in the next section.
In Indonesia, audit opinion refers to Standard Audit (SA) published by the Indonesian Institute of Certified Public Accountants (IAPI), specifically SA 700–705, as well as the provisions of the Audit Board of the Republic of Indonesia (BPK) for government financial statements. This article discusses the meaning of audit opinion, the number and types of opinion under the standard, the stages of forming it, the factors that influence it, and examples of its application in both the corporate and public sectors.
How Many Audit Opinions Are There? 4 or 5?
This question is often confusing because the answer depends on which framework is used. The two are not contradictory — they simply belong to different generations of standards.
| Classic framework — 5 types | Current Auditing Standards — 4 types |
|---|---|
| 1. Unqualified opinion | 1. Unqualified opinion |
| 2. Unqualified opinion with explanatory language | Not a separate opinion type — now an emphasis-of-matter paragraph, without changing the unqualified opinion |
| 3. Qualified opinion | 2. Qualified opinion |
| 4. Adverse opinion | 3. Adverse opinion |
| 5. Not giving an opinion | 4. Disclaimer of opinion |
So the difference lies in just one point. The old framework treated “unqualified opinion with explanatory language” as a stand-alone fourth opinion type. The currently applicable standard no longer treats it as a separate opinion type: when the auditor needs to highlight a matter, they add an emphasis-of-matter paragraph to the report, while the opinion remains unqualified.
In short: following the applicable auditing standard, the answer is 4 types of audit opinions. The number 5 comes from the earlier framework still widely used in course materials, and its extra point is not a new opinion but a variation in how the unqualified opinion is presented.
What Is the Definition of an Audit Opinion?
An audit opinion is the auditor's professional conclusion on the fairness of the financial statements after conducting an audit in accordance with auditing standards. Fairness here does not mean that the statements are completely free from error, but rather that the financial statements are presented fairly in all material respects in accordance with the applicable financial reporting framework (e.g., SAK or SAP).
According to Public Accountant Professional Standards (SPAP), an audit opinion is a statement of opinion submitted by an independent auditor after collecting and evaluating audit evidence sufficient and appropriate. This opinion is stated in the independent auditor's report accompanying the financial statements.
It's important to understand that an audit opinion is not a guarantee that a company is financially sound or free from the risk of fraud. The opinion only assesses whether the financial statements fairly reflect the entity's condition and comply with accounting standards.
What Is the Function of an Audit Opinion?
Audit opinions have several main functions for both entities and external parties:
- Increase the credibility of financial reports. The opinion of the independent auditor provides assurance that the report has been examined objectively.
- The basis for stakeholder decision making. Investors, creditors, and regulators use audit opinions to assess the reliability of financial information before making decisions.
- Benchmark for governance improvement. An opinion other than Unqualified is a signal for management to improve the internal control and reporting system.
- Fulfillment of regulatory obligations. For public companies, state-owned enterprises, and government agencies, an audit opinion is a mandatory compliance requirement.
What Are the Stages of Forming an Audit Opinion?
An audit opinion doesn't emerge instantly, but rather is the result of a systematic audit process. The main stages are as follows.
1. Audit Planning
Auditors develop strategies and audit plan, including understanding the client's business, assessing the risks of material misstatement, and determining materiality level. Careful planning determines the direction and scope of testing.
2. Understanding and Testing Internal Control
The auditor evaluates the effectiveness of the entity's internal controls. If the controls are deemed reliable, auditor can reduce substantive testing; if weak, testing is expanded.
3. Substantive Testing
At this stage the auditor gathers evidence through testing of account balances and transactions—confirmations, document inspections, recalculations, and analytical procedures—to detect material misstatements.
4. Evaluation of Evidence and Formulation of Opinions
The auditor evaluates the sufficiency and appropriateness of the audit evidence and then forms an opinion. The availability of evidence and the degree of material misstatement determine the type of opinion issued.
5. Reporting
The opinion is stated in the independent auditor's report and submitted to management and interested parties.
What Are the 4 Types of Audit Opinions According to the Standard?
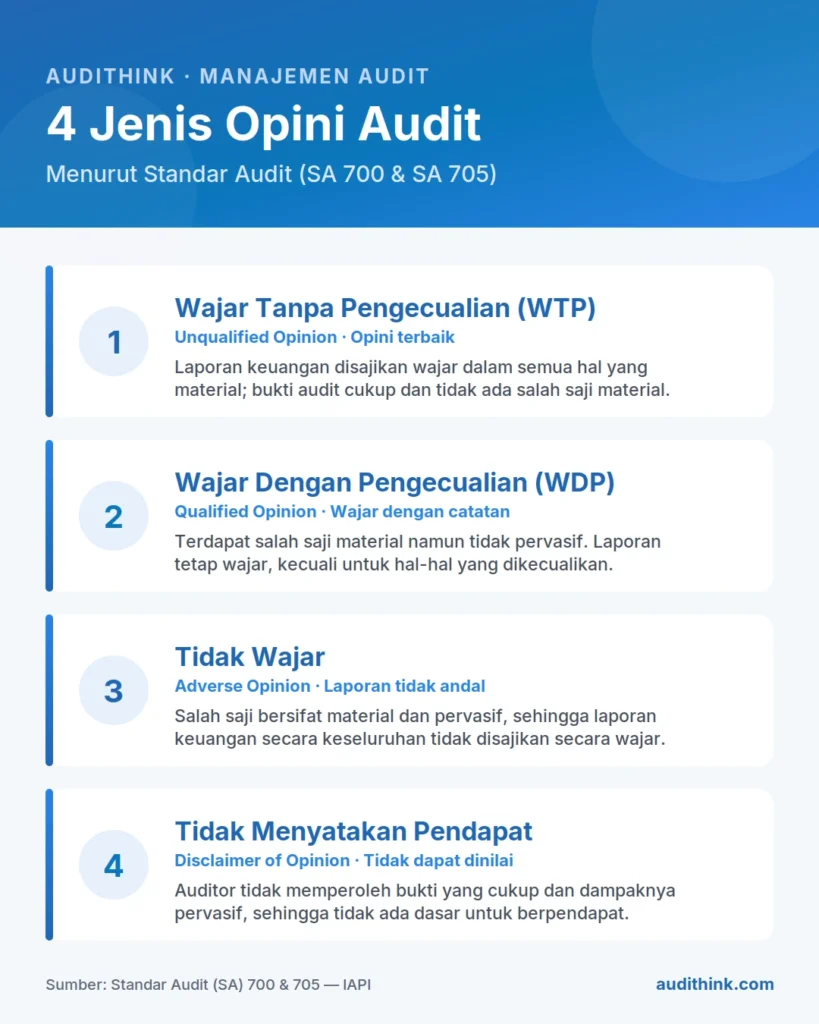
Auditing Standards (SA 700 and SA 705) recognize four types of audit opinions. The following explains each.
1. Unqualified Opinion (WTP)
The best opinion an auditor can provide. An unqualified opinion states that the financial statements are presented fairly, in all material respects, in accordance with the applicable reporting framework. The auditor obtained sufficient evidence and found no material misstatements.
Under certain conditions, the auditor may add paragraph emphasizing a matter (emphasis of matter) without changing the unqualified opinion, for example to highlight uncertainty about the outcome of exceptional litigation or a major catastrophe that has a significant effect on the entity's financial position and has been adequately disclosed in the financial statements. The going concern issue (going concern) is treated differently: a material uncertainty that has been adequately disclosed is reported by the auditor in a separate section of the auditor's report, with a heading that refers to a material uncertainty related to going concern (SA 570), not in an emphasis of matter paragraph.
See also: What is an unqualified opinion? - Definition, examples and how to get
2. Qualified Opinion (WDP)
The auditor provides a WDP opinion when he finds a material misstatement. non-pervasive (not comprehensive), or when sufficient audit evidence cannot be obtained on a particular matter, but the impact is limited. This means that the financial statements as a whole are still fair, except for the excluded matters.
See also: Qualified Opinion: Definition, Basis for Issuance, & Implications
3. Adverse Opinion
An adverse opinion is issued when the auditor concludes that misstatements—either individually or in the aggregate—are material and pervasive, so that the financial statements as a whole do not fairly present the entity's condition. This is a serious signal that the financial statements are unreliable.
See also: Unreasonable opinions on Auditing: definition, implications, and how to avoid
4. Disclaimer of Opinion
The auditor does not express an opinion when unable to obtain sufficient and appropriate audit evidence, and the potential impact of the unavailability of such evidence is material and pervasive. In this situation, the auditor declines to provide an opinion because there is no sufficient basis to conclude that the report is fair.
Important notes: “Disapproval opinion” or disclaimer often mistaken for a separate type. By default, a refusal to give an opinion same as disclaimer of opinion—both refer to the same condition, namely that the auditor does not have a sufficient basis for an opinion.
See also: What is opinion not expressing an opinion? - Definition and basis of awarding
How Does an Auditor Determine the Type of Opinion?
Choosing an opinion follows a standard logic, not free judgment. The auditor answers two questions: what is the nature of the issue, and how widespread is its impact.
| Nature of the issue | Material, not pervasive | Material and pervasive |
|---|---|---|
| The financial statements contain a misstatement | Qualified opinion | Adverse opinion |
| The auditor is unable to obtain sufficient evidence | Qualified opinion | Disclaimer of opinion |
What Does Pervasive Mean in Audit?
Pervasive is a characteristic of an effect that is not confined to a particular item, but spreads to affect the financial statements as a whole. An effect is generally considered pervasive if it is not confined to a specific element or account, if it represents a substantial proportion of the financial statements, or if it concerns disclosures fundamental to the reader's understanding.
This is the concept that separates a qualified opinion from an adverse opinion. If the issue can still be “contained” to a specific item, the opinion is a qualification; if it has spread, the opinion becomes adverse or a disclaimer of opinion.
Comparison Table of 4 Types of Audit Opinions
| Types of Opinions | English terms | Conditions of Grant | Report Reliability Level |
|---|---|---|---|
| Fair without exception (WTP) | Unqualified Opinion | There is no material misstatement; sufficient evidence | High |
| Fair with exceptions (WDP) | Qualified Opinion | Material but not pervasive misstatement | Enough, with a note |
| Unreasonable | Adverse Opinion | Material and pervasive misstatements | Low / unreliable |
| Not Expressing an Opinion | Disclaimer of Opinion | Insufficient evidence, pervasive impact | Cannot be assessed |
Practice: What Opinion Does the Auditor Give? 6 Scenarios and Explanations
Try answering on your own first, then open the explanation. All entities and figures below are fictional and for illustration only. For each scenario, ask three questions based on SA 705: is the problem a misstatement or a lack of evidence, is the amount material, and is the effect pervasive. The explanation of the threshold figures is in the article audit materiality.
Scenario 1. PT Contoh Alfa reports profit before tax of Rp40 billion with overall materiality of Rp2 billion (5% of profit) and total assets of Rp300 billion. Inventory is overstated by Rp6 billion because obsolete goods were not provided for, and management refuses to correct it. There are no other misstatements. What is the appropriate opinion?
Qualified opinion. Rp6 billion exceeds materiality of Rp2 billion, so this misstatement is material. Its effect is limited to one account and is only about 2% of total assets (6 divided by 300), so it is not pervasive. The financial statements as a whole are still fairly presented, except for inventory.
Scenario 2. PT Contoh Bravo has materiality of Rp1.5 billion. The auditor notes three uncorrected misstatements: Rp300 million, Rp250 million, and Rp150 million, in three different accounts. Audit evidence is sufficient. What is the appropriate opinion?
Unqualified opinion. Total misstatements of Rp700 million (300 + 250 + 150) are still below materiality of Rp1.5 billion, so they are not material. Findings do not automatically change the opinion. The auditor still considers qualitative factors, for example whether the misstatement was intentional.
Scenario 3. PT Contoh Charlie has materiality of Rp3 billion. The entity does not consolidate three subsidiaries that it controls, even though the reporting framework requires it. The assets of the three subsidiaries are Rp180 billion, out of group total assets of Rp400 billion. Audit evidence is sufficient. What is the appropriate opinion?
Adverse opinion. This misstatement far exceeds materiality of Rp3 billion. Its effect is pervasive: Rp180 billion is 45% of group assets (180 divided by 400), and it affects consolidated assets, liabilities, revenue, and expenses. Because the auditor has sufficient evidence that the statements are misstated, the opinion is adverse, not a disclaimer of opinion.
Scenario 4. PT Contoh Delta has materiality of Rp2 billion with total assets of Rp250 billion. A flood destroyed the accounting records for the last two years and they cannot be recovered. Trade receivables of Rp90 billion and inventory of Rp70 billion cannot be verified, because alternative procedures do not yield adequate evidence. What is the appropriate opinion?
Disclaimer of opinion. This is an evidence problem, not a misstatement problem. The two accounts total Rp160 billion (90 + 70), or 64% of total assets (160 divided by 250). The possible effects of undetected misstatements could be material and pervasive, so the auditor has no basis for an opinion.
Scenario 5. PT Contoh Echo has materiality of Rp2 billion with total assets of Rp250 billion. The auditor was appointed after year-end and so did not attend the physical inventory count, and alternative procedures do not provide adequate evidence over inventory worth Rp7.5 billion. Other accounts were audited without obstacles. What is the appropriate opinion?
Qualified opinion. The problem is again evidence. The possible misstatement in inventory could reach Rp7.5 billion, above materiality of Rp2 billion, so it could be material. However, its value is 3% of total assets (7.5 divided by 250) and it is limited to one account, so it is not pervasive. Compare with Scenario 4: the same evidence problem, but with a much wider scope.
Scenario 6. PT Contoh Foxtrot has materiality of Rp2 billion. The financial statements are fairly presented and evidence is sufficient. After the reporting date but before the auditor's report is issued, the main warehouse burns down with an estimated loss of Rp25 billion. This event has been adequately disclosed in the notes to the financial statements. What is the appropriate opinion?
Unqualified opinion, with an emphasis of matter paragraph. There is no material misstatement and no evidence limitation, so the opinion does not change. If the auditor judges that the event is fundamental to users' understanding, the auditor may highlight it in an emphasis of matter paragraph (SA 706). That is why this paragraph is not a fifth type of opinion. If the disclosure is inadequate, only then can the opinion change to qualified or adverse.
Notes: the percentages above are only an aid. SA 705 sets no fixed figure for “pervasive”. What decides it is the auditor's professional judgment on the breadth of the effect.
How Does Audit Opinion Work in the Public Sector (BPK) Context?
For government financial reports—both the Central Government Financial Report (LKPP), Regional Government Financial Report (LKPD), and BUMN/BUMD—opinions are provided by the Audit Board of Indonesia (BPK) with four types of opinions that are equivalent to audit standards:
- WTP (Unqualified Opinion) — highest opinion, often becomes the performance target of government agencies and state-owned enterprises.
- WDP (Fair With Exceptions)
- TMP (Disclaimer)
- TW (Unnatural)
For public sector entities and state-owned enterprises, obtaining an unqualified opinion from the BPK is not just a formality, but an indicator of accountability and good financial governance (good governanceThis opinion is often part of the key performance indicators (KPI) and is of concern to the Inspectorate and the Internal Audit Unit (SPI).
What Factors Influence an Audit Opinion?
Several factors determine the type of opinion the auditor gives:
- Sufficiency and accuracy of audit evidence. The more complete and reliable the evidence, the stronger the auditor's basis for issuing an unqualified opinion. Limited evidence can lead to an unqualified opinion or a disclaimer.
- The level of materiality and pervasiveness of misstatements. Minor misstatements may be ignored; material misstatements determine whether the opinion is WDP, adverse, or other.
- Effectiveness of internal control. Weak internal controls increase the risk of misstatement and affect the extent of testing and the auditor's conclusions.
- Compliance with accounting standards. Material deviations from SAK/SAP can reduce the quality of the opinion.
- Going concern issues. Significant doubt about the entity's ability to continue as a going concern can lead to a material uncertainty being reported in a separate section. If the disclosure is inadequate, the opinion may be modified.
What Are Examples of Audit Opinion Application?
The following illustrates how audit opinions arise in practice:
- Public companies obtain WTP after the auditor ensures that the financial statements are presented fairly in accordance with SAK, with adequate internal controls and complete audit evidence.
- A listed issuer receives an unqualified opinion with a material uncertainty related to going concern section because it has a working capital deficit that raises significant doubt, even though the disclosure is adequate. The opinion remains unqualified, but readers are alerted to the sustainability risk.
- BUMD receives WDP from auditors due to the recording of fixed assets that cannot be fully verified, but does not affect the report as a whole.
- Government agencies obtain TMP from the BPK Due to limited evidence on a number of material transactions, the BPK was unable to conclude the fairness of the report.
Audit Opinion FAQs
How many audit opinions are there?
According to the applicable Auditing Standards (SA 700–705), there are 4 types of audit opinions: unqualified opinion, qualified opinion, adverse opinion, and disclaimer of opinion.
Why do some references mention 5 audit opinions?
The classic framework treats “unqualified opinion with explanatory language” as a separate opinion type, bringing the total to five. The current standard no longer treats it as a separate opinion type — it is now an emphasis-of-matter paragraph that does not change the unqualified opinion.
What is an audit opinion in brief?
The audit opinion is the auditor's official statement regarding whether the financial statements are fairly presented in accordance with applicable accounting standards. This opinion is the final conclusion of the audit process.
What does pervasive mean in audit?
Pervasive is a characteristic of an effect that is not confined to a particular item, but spreads to affect the financial statements as a whole. This is the concept that separates a qualified opinion from an adverse opinion and a disclaimer of opinion.
What does WTP (Unqualified Opinion) mean?
Unqualified Opinion (WTP) means the financial statements are presented fairly in all material respects in accordance with the applicable reporting framework. This is the best opinion an auditor can provide.
What is the difference between an unfair opinion and not stating an opinion?
An adverse opinion is issued when there is a material and pervasive misstatement (the auditor has evidence that the report is incorrect). A disclaimer of opinion is issued when the auditor does not have sufficient evidence to conclude at all.
Who provides the audit opinion for government financial statements?
For government financial reports and some BUMN/BUMD, opinions are given by the Audit Board of Indonesia (BPK) in four categories: WTP, WDP, TMP, and TW.
Does a WTP opinion guarantee that the company is free from fraud?
No. An unqualified opinion (WTP) only assesses the fairness of the presentation of financial reports according to standards, not a guarantee of fraud-free or absolute financial health of the company.
Read also — audit engagements, fees, and tenure:
- Role of Audit Services, types, and Tips for choosing a professional provider
- Audit rotation: definition, objectives, types, examples and regulations
- Audit Tenure: Definition, Benefits, formula, and how to calculate
- How to see Audit fees in financial statements
- Audit Report Lag: definition, factors, and cases in Indonesia
Manage Your Internal Audit Process in a More Structured Way
A quality audit opinion begins with a well-documented audit process—from planning and testing to reporting findings. For internal audit teams in state-owned enterprises (BUMN), regional-owned enterprises (BUMD), and government agencies, managing this entire cycle manually often makes it difficult to track evidence and maintain consistent working papers.
Audithink helps internal audit teams manage planning, working papers, findings, and follow-up in one integrated platform that supports SPIP, Risk-Based Internal Audit, and Good Corporate Governance.
Schedule an Audithink demo to see how our platform can strengthen internal audit and governance processes in your organization.